Actual Cash Value
Share


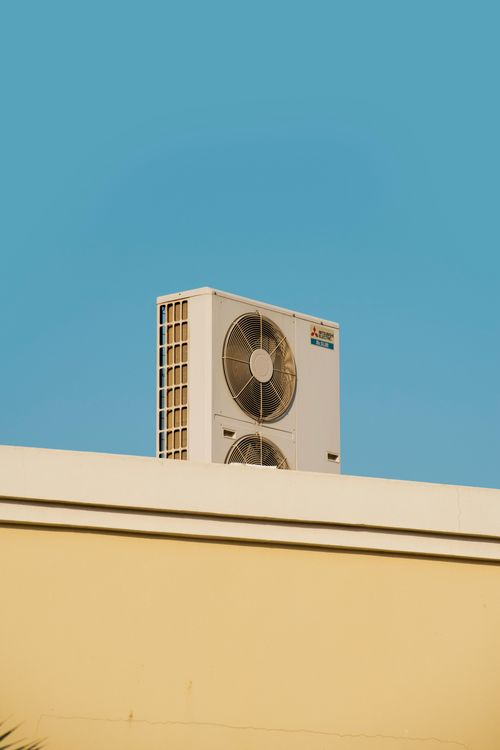
Your furnace dies on the coldest night of the year. You call your insurer expecting home insurance broken furnace Canada coverage. They deny your claim. Here's why: Canadian home insurance covers sudden disasters like fires and burst pipes, not equipment that stops working because it's old. Home insurance doesn't cover maintenance costs.
Your policy type determines what gets covered. Named perils policies cover specific events listed in your contract. All-risk policies cover everything except what's explicitly excluded. Both types handle furnace and HVAC damage the same way, regardless of the cause.
Covered causes include fire, lightning, sudden water damage, electrical surge, and vandalism. If a tree falls through your roof and crushes your air handler, that's covered. If lightning strikes and damages your HVAC control board, you're protected. Watch for: gradual wear, rust, corrosion, and mechanical breakdown from age are explicitly excluded.
The exclusions matter more than the covered perils for does home insurance cover HVAC questions. Your furnace and ductwork are part of your insured building. Damage from a covered event gets paid. Internal failure from aging parts doesn't.
Home insurance protects against sudden, accidental, unforeseen events. Maintenance issues don't qualify. Insurers treat equipment wear as an expected homeowner responsibility, just like appliance failure. Your 20-year-old furnace dying isn't sudden or unexpected.
Home insurance excludes predictable events. A furnace reaching the end of its lifespan is predictable. Compare these scenarios: A furnace that dies of old age versus a furnace damaged by an electrical fire. The first is maintenance. The second is a covered peril.
This distinction shapes every furnace breakdown home insurance Canada claim. Insurers pay for disasters, not deterioration. Your premiums reflect this reality. Home insurance premiums increased 45% between December 2019 and December 2025. If policies covered every equipment failure, premiums would be even higher.
Equipment breakdown coverage is an optional endorsement that covers sudden mechanical or electrical breakdown of home systems. This coverage typically includes furnaces, boilers, heat pumps, central air conditioning, water heaters, and electrical panels. It responds when these systems fail suddenly due to a covered mechanical or electrical cause.
Consider this endorsement if your home has older systems or aging equipment. Replacement costs for high-efficiency furnaces and heat pumps can reach tens of thousands of dollars. This home insurance mechanical breakdown Canada add-on bridges the gap between standard coverage and expensive manufacturer warranties.
Four scenarios show how cause determines coverage. A burst pipe floods your furnace room. The water destroys your furnace. This claim typically gets approved because sudden water damage is a covered peril. The resulting damage to your home and the furnace itself may be covered under your base policy.
An electrical surge fries your HVAC control board during a storm. Named-peril and all-risk policies generally cover this because electrical surge is a listed peril. A house fire damages your ductwork and furnace. Covered—fire is the most clearly covered peril in any policy.
Your 15-year-old furnace simply stops working one morning. No fire, no water, no external cause. Not covered without an equipment breakdown endorsement.
The distinction between the system failing and damage caused by that failure matters. Your base policy covers collateral damage from many sudden failures. Equipment breakdown coverage extends to the system itself.
Read your policy wording. Find the named perils section and the exclusions section. These tell you what's covered and what's not. Standard wordings list mechanical breakdown alongside wear and tear as excluded causes.
Check whether mechanical or equipment breakdown coverage is already included in your policy. Some insurers bundle it into premium packages. Others offer it as a separate endorsement. Don't assume based on your premium level. High-value home policies don't automatically include equipment breakdown coverage.
Ask your insurer or broker directly. Specify that you want to know about HVAC coverage home insurance Canada for both sudden perils and mechanical failure. Get the answer in writing. If you have equipment breakdown coverage, confirm the limits, deductibles, and covered equipment list. Policies typically include per-occurrence limits of $50,000 to $100,000 for residential equipment breakdown coverage.
Start by calling a licensed HVAC technician for diagnosis and written documentation. You need a professional assessment of what failed and why. The cause determines whether you have coverage.
Determine whether the cause falls under a covered peril or is simple wear and tear. If the technician finds that your heat exchanger cracked due to age, that's mechanical breakdown. If they find that an electrical surge damaged your control board, that's a covered peril.
File a claim only if the cause falls under a covered peril or if you have equipment breakdown coverage. Filing claims that will be denied wastes time and can affect your claims history. Get repair or replacement quotes if the damage isn't covered. Budget for the cost yourself.
Insurely helps Canadian homeowners compare insurance options and understand their coverage. Use resources like this to clarify your coverage before problems arise.
Add mechanical or equipment breakdown coverage to your policy. This endorsement fills the gap between standard coverage and expensive repairs. Actual costs vary by province, home characteristics, and insurer.
Keep annual maintenance and inspection records for your furnace and HVAC system. Maintenance records prove you acted responsibly.
Consider an extended warranty for systems nearing the end of their expected lifespan. These warranties work differently than insurance endorsements but can cover repairs. Budget for eventual replacement costs based on your system's age. Most furnaces last 15 to 20 years. Plan accordingly.
Construction costs have soared 66% since 2019, putting upward pressure on home insurance premiums. Equipment replacement costs have climbed along with them.
Confirm whether your policy is named perils or all-risk. This determines your baseline coverage. Check if mechanical or equipment breakdown coverage is included or optional. Don't assume it's part of your base policy.
Keep annual furnace and HVAC maintenance records on file. Store service receipts and inspection reports. These documents protect your claim if a dispute arises. Know your system's age and expected lifespan. A 5-year-old furnace has a different risk than a 20-year-old unit.
Get a repair or replacement cost estimate before filing a claim. Sometimes paying out of pocket makes more sense than filing a claim that might be denied. Compare equipment breakdown add-on costs across at least three insurers. Pricing varies significantly between companies.
No. Standard policies exclude mechanical breakdown from age or wear. Equipment breakdown endorsements may cover sudden mechanical failure if added to your policy. Age-related failure without an external cause isn't covered.
Named perils covers only listed events like fire or lightning. All-risk covers everything except exclusions. Both exclude mechanical breakdown from age. Both require equipment breakdown endorsements for internal mechanical failure.
Costs vary by province, home age, and insurer. Anecdotal reports suggest $30 to $50 annually with a $500 deductible. Get quotes from multiple insurers. Actual pricing depends on your specific property and risk factors.
Possibly. Lack of maintenance is a common reason for claim denials. Industry sources confirm that failing to maintain HVAC systems leads to coverage disputes. Keep service records to prove responsible maintenance.
Heavy snow can collapse roofs and cause serious damage. Learn what snow load damage is, if home insurance covers it, and how to protect your home in Canada.
Wondering if your tenant insurance covers your roommate in Canada? Learn when roommates are covered, when they aren't, and the smartest way to share coverage.
What is loss assessment coverage in condo insurance? Learn how it protects Canadian condo owners from unexpected special assessments and shared building costs.
A home inventory can make or break your tenant insurance claim. Learn how to document your belongings properly in Canada and what insurers need to see.

Ice dams can cause serious roof and water damage. Find out whether home insurance covers ice dam damage in Canada and how to protect your home this winter.
Does home insurance cover burst or frozen pipes in Canada? Learn what water damage is covered, what's excluded, and how to prevent pipe damage this winter.


