InsuranceActual Cash Value
Share


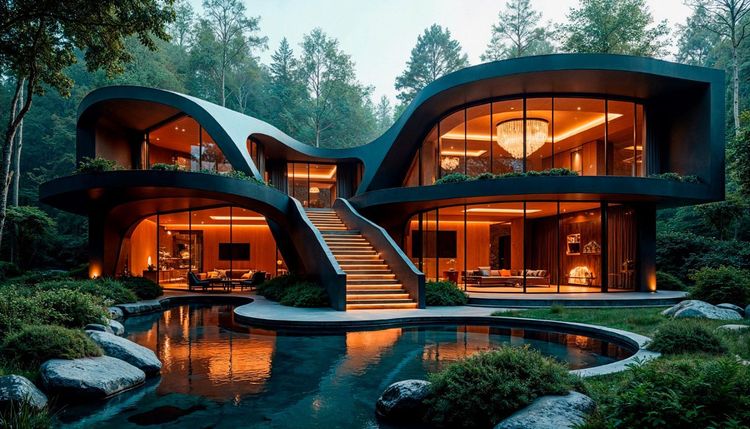
Luxury homes in Ontario need more than basic coverage. High value home insurance Ontario adds the protection most policies leave out. Get higher limits, better service, and coverage designed for rare, custom, or high-worth properties.
A standard policy treats every house the same. But a luxury home in Ontario deserves coverage that matches its worth. Fine finishes, rare materials, and custom features carry risks most policies ignore. High value home insurance doesn’t guess—it’s built to protect the life you’ve worked hard to create. One missed detail could cost more than you think.
If you own a luxury property in Ontario, standard home insurance might fall short. High-value homes need higher coverage limits, more protection options, and faster service when problems happen. High-value home insurance is built for homeowners who need more than the basics.
Not every property qualifies. Most providers define a high-value home as one with a replacement value over $1 million. But some insurers start coverage at $750,000. It’s not just about price. Unique design, rare materials, and luxury finishes often raise the cost of repairs and replacement. So does custom architecture, imported flooring, or specialty appliances. The goal is to protect the full value of your home and everything inside it.
High value home insurance in Ontario offers much broader protection than a standard policy. Many standard policies cap payouts on things like jewellery, artwork, or wine collections. High value policies don’t just raise those caps—they often include full replacement value coverage, without depreciation.
Replacement cost coverage matters. A luxury kitchen with custom cabinetry and imported counters will cost far more than what standard insurance will pay out. High value policies factor in quality, not just function.
The policies also tend to include more generous liability coverage. If someone is injured on your property or sues for damages, your liability limit could make a huge difference. Legal costs and medical expenses add up quickly, especially when claims involve high-net-worth families.
A good high-value home insurance policy includes:
Some providers even include concierge-level service. That might mean a personal claims advisor, faster repairs, or direct access to restoration experts.
It also covers high-value property features like wine cellars, smart home systems, saunas, gyms, and custom furniture. Some policies will be extended to cover luxury vehicles or high-value collections stored at home.
Not every insurance company handles high-value homeowners. Some stick to standard home insurance. In Ontario, a few known providers in this space include Aviva Ovation, Chubb, Northbridge, and Intact Prestige.
Working with a broker experienced in luxury insurance is key. They understand the value of unique homes and will recommend policies with the right mix of coverage, support, and speed.
When shopping, compare home insurance quotes from at least three companies. Ask about coverage limits, claims service, and the kind of documentation you’ll need for valuables.

Premiums for high value home insurance in Ontario vary based on the size, location, and details of the home. Larger homes with rare materials or remote locations tend to cost more to insure. So do homes with a history of multiple claims or with high risk features like pools, wood stoves, or large outbuildings.
You might pay $2,000 to $5,000 a year or more. The average is often around $3,000, but high-end homes in Toronto or Muskoka may see rates well beyond that. Bundling with auto or business insurance will lower premiums.
Security systems, sprinklers, and preventative maintenance may reduce costs. So can raising your deductible or switching to annual payments.
Not all claims are the same. When the worst happens, the right insurance makes recovery smoother.
Here are some situations where high value home insurance proves its worth:
High value policies will be adjusted based on your lifestyle. If you run a business from home, you may need business insurance add-ons. If you host events, you might want extra liability protection.
If you collect fine art, equipment breakdown protection could matter more than you think. Some policies also offer loss prevention inspections or risk mitigation services at no cost.
A good home insurance policy for high value homes isn’t something you set and forget. Values change, property upgrades happen, and collections grow. Review your policy annually. Make sure coverage matches your current home and possessions.
Look at:
Ask your broker to walk through the full policy. Confirm what’s covered and what’s not. Be clear on exclusions and coverage limits.
High value home insurance in Ontario protects more than bricks and drywall. It protects your lifestyle, your collections, and your peace of mind. If you own a luxury home, standard home insurance policies often fall short. High value home coverage fills the gaps with better options built for bigger risks.
Claims on high value properties are often complex. Repairs might involve custom construction or imported finishes. Contents may include fine art, vintage wine, or one-of-a-kind furniture. That’s where specialized insurance products matter. The right policy goes beyond basics and covers what’s truly at risk.

Instead of gaps, you get guarantees. Instead of capped contents, you get flexible protection. Many luxury homes have unique features that need higher limits and specific coverage options. You don’t want to find out after a claim that your policy missed something important.
High-value home insurance provides you with extra support during a loss. That might include extended home coverage, increased limits for valuables, or additional living expenses while repairs happen. You may also get coverage for liability tied to staff or events at your property.
Unlike standard home insurance policies, high value plans offer broader coverage, fewer exclusions, and more control. The cost is higher, but so is the protection.
For anyone with a high value home in Ontario, the right insurance is more than a line item. It’s a long-term shield for your property, your lifestyle, and the assets you’ve worked hard to protect.
Disclaimer: This blog post is for general information only and does not constitute personalized advice. Please consult a licensed insurance broker to determine the insurance solution that best fits your specific needs.
Homes requiring rebuild costs above $750,000 or contents coverage exceeding $175,000 typically qualify. Properties around $1.3 million clearly need specialized programs. Custom architecture and heritage features also trigger high-value classification.
No public average exists. Premiums depend on rebuild cost, location, contents value, claims history and risk-mitigation features. Properties facing higher climate exposure cost more following record $8.55 billion weather losses in 2024
Specialty MGAs like CHES Special Risk and Aon private client divisions dominate this market. Standard insurers rarely quote these risks directly. Work with brokers specializing in affluent homeowners for proper placement.
Heavy snow can collapse roofs and cause serious damage. Learn what snow load damage is, if home insurance covers it, and how to protect your home in Canada.
Wondering if your tenant insurance covers your roommate in Canada? Learn when roommates are covered, when they aren't, and the smartest way to share coverage.
What is loss assessment coverage in condo insurance? Learn how it protects Canadian condo owners from unexpected special assessments and shared building costs.
A home inventory can make or break your tenant insurance claim. Learn how to document your belongings properly in Canada and what insurers need to see.

Ice dams can cause serious roof and water damage. Find out whether home insurance covers ice dam damage in Canada and how to protect your home this winter.
Does home insurance cover burst or frozen pipes in Canada? Learn what water damage is covered, what's excluded, and how to prevent pipe damage this winter.


